
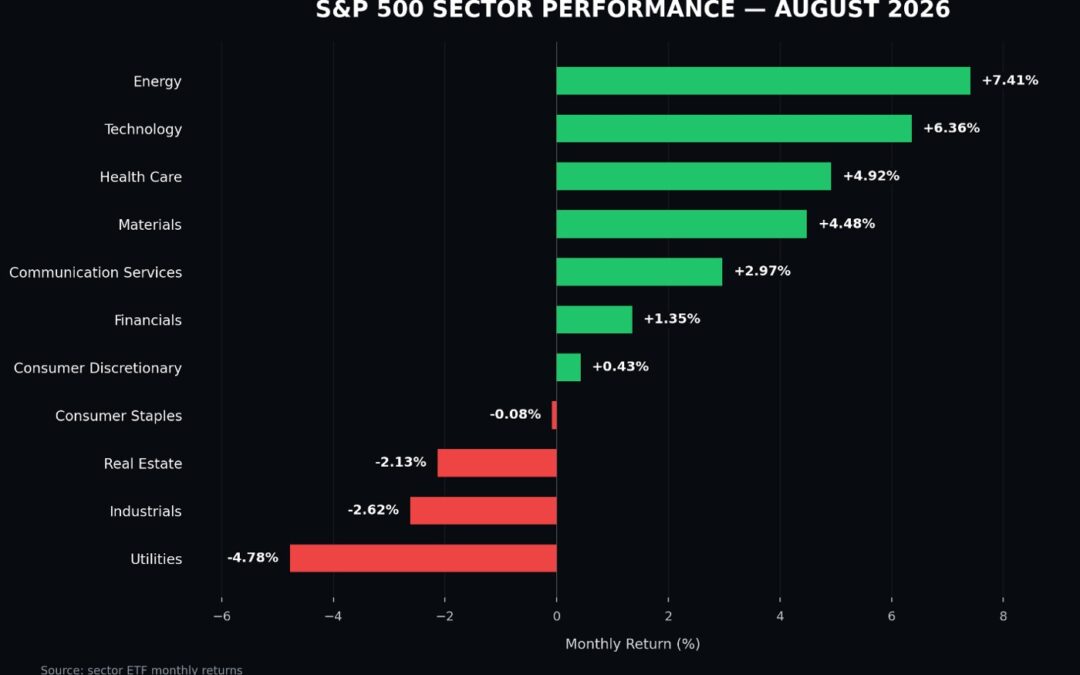
August may have marked an important change in the market environment.
Over the past two years, Artificial Intelligence has been the dominant investment narrative across global equity markets, with investors willing to assign extremely high valuations to companies exposed to semiconductors, data centres and computing infrastructure.
That willingness now appears to be becoming more selective (eg., State Street SPDR S&P Semiconductor ETF dropped almost 30% from previous highs).
The long-term potential of AI remains intact and demand for computing infrastructure remains exceptionally strong. However, investors increasingly appear less willing to accept very high valuations for business models whose returns remain uncertain and far into the future.
The question is gradually shifting from: “How large can Artificial Intelligence become?” to: “Who will ultimately capture the economic returns generated by this investment cycle?”
At the same time, another potentially important development is emerging.
After several months of deteriorating liquidity conditions, our liquidity indicators have recently shown a significant improvement, with the Permanent Portfolio recording a sharp upward move.
If confirmed in the coming months, this could represent an important positive change in the macroeconomic environment and potentially extend the current bull market further.